Market Overview and Industry Significance of Blended Cement
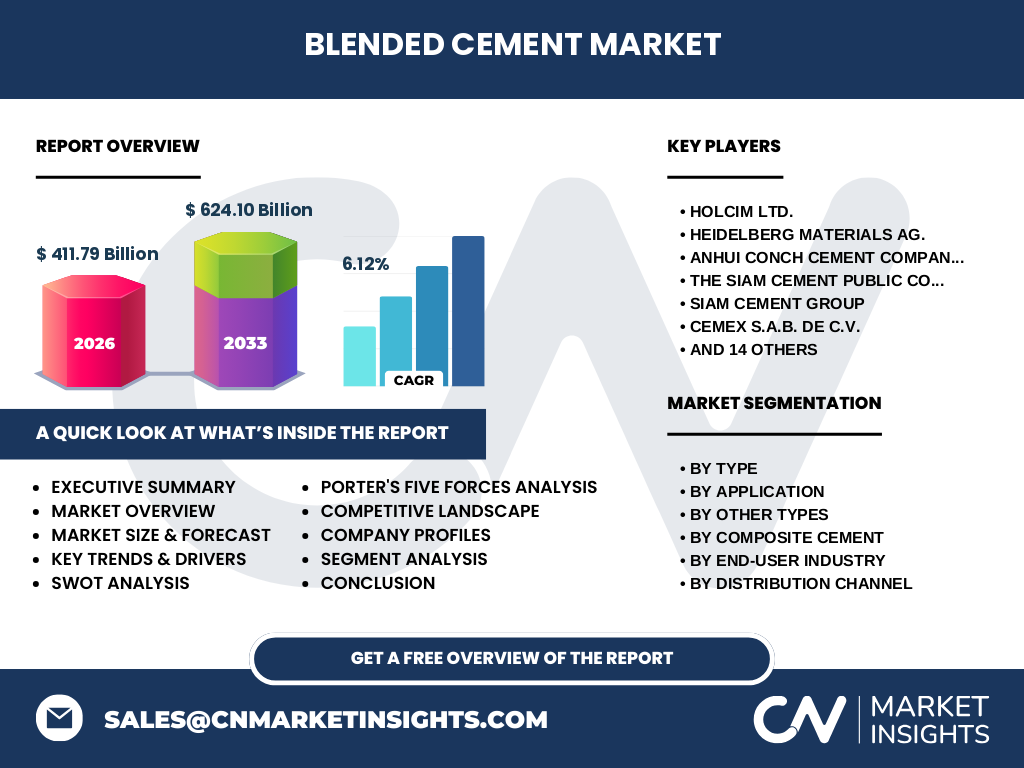
Our analysis indicates the Blended Cement Market is valued at 411.79 Billion in 2026. This sector encompasses supplementary cementitious materials like fly ash, GGBFS, and calcined clays blended with clinker. Driven by strict carbon emission mandates from bodies like the EPA and EU, the industry plays a vital role in lowering the clinker-to-cement ratio, significantly reducing global construction-related carbon footprints.
Structural Growth Drivers and Market Restraints
The market thrives on rapid urbanization and infrastructure investments, offset by high energy costs for grinding supplementary materials. Strict environmental regulations by the ISO and local building codes compel developers to adopt sustainable binders. Logistical hurdles in transporting raw materials like rice husk ash and silica fume from rural agricultural hubs to urban ports remain a critical restraint for tier-2 manufacturers.
Emerging Trends in the Blended Cement Market
A major shift toward ternary blended cement and limestone-calcined clay cement is reshaping manufacturing protocols. Producers are increasingly utilizing industrial by-products like ground granulated blast furnace slag. Decarbonization commitments by major urban developers dictate that suppliers adopt low-carbon formulations to secure municipal infrastructure supply contracts.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic caused severe supply chain disruptions and labor shortages, temporarily halting transport operations at major maritime hubs. However, government stimulus packages targeting infrastructure modernization catalyzed a robust rebound. Post-pandemic recovery has accelerated the adoption of automated batching plants and digital distribution channels, mitigating future supply chain vulnerabilities.
Competitive Benchmarking and Market Concentration
The Blended Cement Market industry trends highlight consolidation among multinational giants. Holcim Ltd., CEMEX S.A.B. de C.V., and Heidelberg Materials AG. dominate through vast limestone reserves and strategic supplementary material sourcing. Regional titans like UltraTech Cement Limited and Anhui Conch Cement Company Limited leverage localized production networks to maintain aggressive cost leadership.
Executive Summary: Blended Cement Market Synthesis
Driven by stringent environmental policies and sustainable construction mandates, the market is poised for robust expansion. Our research projects growth from 411.79 Billion in 2026 to 624.10 Billion by 2033, registering a 6.12% CAGR. Strategic investments in calcined clay and ternary blends will separate market leaders from legacy producers.
Market Forecast from 2027 to 2033
The data projects consistent expansion, driving market valuation from 411.79 Billion in 2026 to reach 624.10 Billion by 2033. Achieving this 6.12% CAGR relies heavily on increased government spending on resilient marine construction and urban transportation infrastructure across developing economies.
Segmentation Analysis of Blended Cement
Segmentation spans types such as Portland Pozzolana Cement, Portland Slag Cement, and Composite Cement, utilized across precast and cast-in-place applications. Specialized variants like rice husk ash and silica fume-based products cater to niche high-performance architectural needs, while distribution is split across direct sales, retail, and wholesale channels.
Geographic Distribution and Regional Performance
Regional performance varies based on local regulatory stringency and raw material availability. Asia-Pacific leads consumption due to aggressive housing initiatives and infrastructure projects in India and China, supported by local firms like Dalmia Bharat Limited and Tianrui Group. Meanwhile, European markets prioritize ultra-low carbon composite cements to meet stringent EU directives.
In-Depth Regional Review
In North America and Europe, stringent green building certifications dictate procurement choices. Conversely, emerging economies in Asia and Latin America focus on cost-effective fly ash and slag blends to manage rapid urban expansion. Localized logistical networks operated by players like The Siam Cement Public Company Limited ensure steady regional supply despite port congestions.
Strategic Positioning of Leading Companies
Industry leaders focus on proprietary low-carbon formulations and vertical integration. Taiheiyo Cement Corporation and Buzzi Unicem S.p.A. invest heavily in alternative fuel combustion and slag granulators. Meanwhile, firms like Lafarge S.A. and Titan Cement Group emphasize strategic partnerships with steel mills to secure steady supplies of blast furnace slag.
Porter's Five Forces Analysis
Industry rivalry is intense, shaped by high capital requirements and established multinational footprints. Supplier power remains moderate to high depending on regional access to quality fly ash and GGBFS. Threat of substitution is mitigated by strict structural performance standards governing major transportation and marine infrastructure projects.
SWOT Analysis of the Industry
Key strengths include reduced carbon output and enhanced durability against sulfate attacks. Weaknesses involve variable curing times for certain pozzolanic blends. Opportunities abound in green-rated commercial developments, while threats stem from volatile energy pricing and stringent transport regulations governing raw material haulage.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with the extraction of limestone and sourcing of industrial by-products like fly ash and slag. Midstream processing involves precise grinding and blending in energy-intensive mills. Downstream distribution relies on wholesale distributors and direct sales to residential contractors and massive marine construction projects.
Investment Insights and High-Potential Areas
High-potential capital allocation targets calcined clay production lines and ternary blended cement technologies. Investors should prioritize firms with integrated supply chains capable of navigating fluctuating raw material costs. Targeted acquisitions of regional slag granulators offer immediate market entry into high-growth urban construction corridors.
Conclusion and Key Takeaways
The market represents a critical pillar of sustainable heavy construction. Reaching the projected 624.10 Billion valuation requires continuous technological innovation in clinker substitution. Strategic agility in securing raw materials will ultimately dictate long-term profitability for key stakeholders.
Research Methodology for Baseline Estimates
Baseline estimates are triangulated by combining customs trade registry data, primary stakeholder interviews with executives from ACC Limited and Cemex, and secondary macroeconomic indicators from global trade bodies. Rigorous econometric modeling reconciles conflicting data points to establish accurate market sizing.
Scope of the Report and Coverage Parameters
This comprehensive analysis covers global market dynamics from 2026 to 2033, evaluating multiple cement types, applications, and end-user verticals. Analytical limitations include unforeseen geopolitical disruptions impacting international clinker shipping lanes and regional regulatory shifts regarding industrial by-product classifications.
Recent Developments and Strategic Moves
Recent market activity features strategic joint ventures and capacity expansions aimed at reducing carbon footprints. InterCement Participacoes SA and Zuari Cement Limited have launched advanced blended product lines utilizing locally sourced industrial wastes. These initiatives reflect a broader industry pivot toward circular economy principles and enhanced operational efficiency.